Enter your monthly amount, expected return and time period. This SIP calculator shows your estimated corpus, a yearly growth chart and a year-by-year schedule.
SIP Calculator
Estimate your future corpus with an optional yearly step-up.
Investment schedule (yearly snapshot)
| Year | Invested (₹) | Returns (₹) | Corpus (₹) |
|---|
Illustrative estimates only. Actual returns vary with the market.
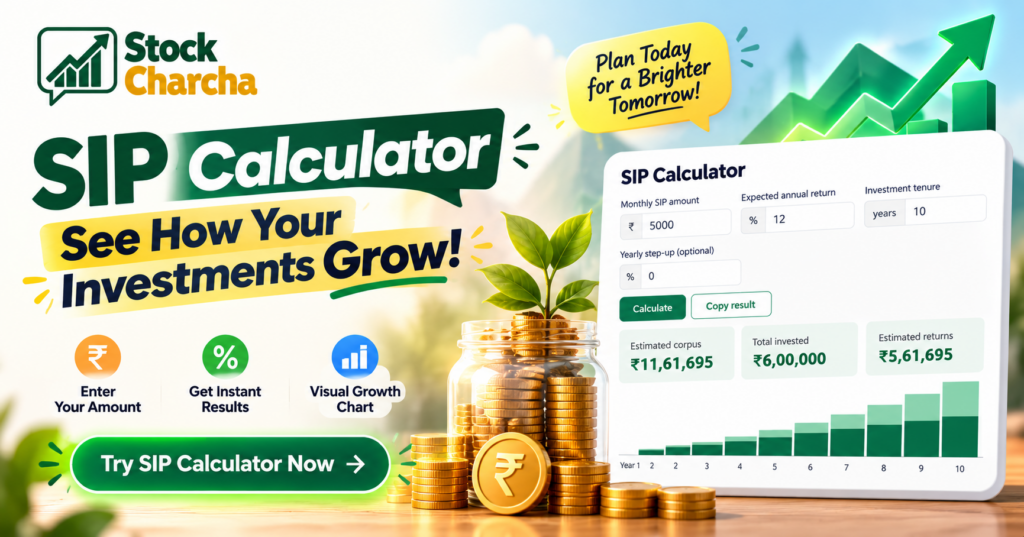
Most people type ₹5,000 into a SIP calculator, glance at one big number and close the tab. A better habit is to run it three times with small changes and compare the results. The gaps between those numbers teach you more than the headline figure ever will.
How do you use this SIP calculator?
- Enter the amount you can invest every month, in rupees.
- Add the yearly return you expect. Pick a number you can defend, not the highest one you have heard.
- Set the tenure in years.
- Add a yearly step-up if your salary grows. Leave it at 0 for a flat SIP.
- Press Calculate, then use Copy result to save a summary of the numbers.
Stock Charcha built this tool for first-time investors, so it shows your invested amount and your returns separately. That split is the useful part: it shows how much of the final corpus is your own money and how much is compounding.
How does the SIP calculator work out the result?
The SIP calculator treats each instalment as invested at the start of the month and compounds it monthly. Compounding simply means your returns also start earning returns.
Corpus = P × [((1 + i)n − 1) ÷ i] × (1 + i)
Here P is your monthly amount, i is the monthly rate (annual return ÷ 12 ÷ 100) and n is the number of months. With a step-up, the calculator raises P once every 12 months and repeats the same maths.
What does a worked example look like?
Say you invest ₹5,000 a month at an illustrative 12% return. Here is what the SIP calculator shows as the tenure grows.
| Tenure | Total invested | Estimated corpus | Estimated returns |
|---|---|---|---|
| 10 years | ₹6,00,000 | ₹11.62 lakh | ₹5.62 lakh |
| 15 years | ₹9,00,000 | ₹25.23 lakh | ₹16.23 lakh |
| 20 years | ₹12,00,000 | ₹49.96 lakh | ₹37.96 lakh |
Stock Charcha keeps these examples round on purpose, so you can check them by hand. From 10 to 20 years your own money only doubles, but the corpus grows to more than four times. These figures are illustrative, not a promise, and real returns change every year.
How much does the return you enter change the SIP calculator result?
A lot more than most people expect. Here is the same ₹5,000 a month for 10 years, with total investment fixed at ₹6,00,000.
| Assumed return | Estimated corpus |
|---|---|
| 8% | ₹9.21 lakh |
| 10% | ₹10.33 lakh |
| 12% | ₹11.62 lakh |
Each two-point step moves the SIP calculator result by about ₹1.1 to ₹1.3 lakh. Plan with the lower number and treat the higher one as a bonus.
Is a yearly step-up worth adding to your SIP?
For most salaried people, yes. Run ₹5,000 for 10 years at 12% with a 10% yearly step-up and the calculator shows about ₹9.56 lakh invested and a corpus near ₹16.87 lakh. A flat SIP gives ₹6 lakh invested and ₹11.62 lakh.
A 10% step-up means ₹5,000 becomes ₹5,500 in year two and ₹6,050 in year three. You put in about ₹3.56 lakh more and end with about ₹5.25 lakh more. Try your own raise percentage in the step-up box.
How much SIP do you need for a specific goal?
Work backwards from the goal. To reach ₹25 lakh in 10 years at an illustrative 12%, you would need roughly ₹10,760 a month, not ₹5,000. Type that amount into the SIP calculator to confirm it. Stretch the tenure to 15 years and the same ₹25 lakh needs only about ₹4,950 a month. A down payment, a child’s education fund or a retirement top-up all work the same way.
What does this SIP calculator leave out?
At Stock Charcha we keep the assumptions visible so you can question them. It does not deduct the fund’s expense ratio, the yearly fee a fund charges, so enter a net return for a safer result. It also ignores capital gains tax and inflation, which means a corpus 15 to 20 years away buys less than the number suggests. Check current tax rules on the Income Tax Department website as of today before planning around post-tax figures.
Real SIPs also do not grow in a straight line. For fund NAVs and category data, use AMFI. Mutual fund investments are subject to market risks. Read all scheme related documents carefully before investing.
Where should you go after using the SIP calculator?
Once you have a target, pick a fund type that fits your timeline. Our guide to the types of mutual funds explains the options simply. If you are unsure whether to invest monthly or all at once, read SIP vs lump sum.
New to the idea? Start with what is SIP in mutual funds, then read why time in the market beats timing it. Run the SIP calculator again with a lower return and a higher amount, and let the gap guide your plan.
Founder of Stock Charcha. Stock market enthusiast, actively investing since November 2022. About the author
Educational content only. This page is not personalised financial advice. Please do your own research or speak to a SEBI-registered adviser before investing, and read our disclaimer.
Frequently asked questions
Is the result from a SIP calculator guaranteed?
No. SIPs in equity funds are market-linked, and a calculator assumes one steady return every year. Real returns rise and fall, and some years can be negative. Treat the result as a planning estimate, not a promise.
Can I use the SIP calculator for debt fund SIPs?
Yes, the maths is the same. Just enter a lower expected return, because debt funds usually return less than equity funds. Use a net figure, after the fund’s expense ratio, for a more realistic result.
Is SIP return taxed like FD interest?
No. Gains from equity funds fall under capital gains tax, while FD interest is added to your income and taxed at your slab rate. Rates and holding periods change, so verify the current rules before you file.
What happens if I miss a SIP payment?
Most fund houses simply skip that instalment, usually without a penalty. Several missed payments in a row can get the SIP cancelled, and some banks charge a small fee for a failed debit, so keep enough balance.
Can I stop my SIP anytime?
Most open-ended funds let you pause or stop a SIP whenever you like. ELSS tax-saving funds lock each instalment for three years, and some funds charge an exit load on early withdrawals, so check the scheme documents first.